
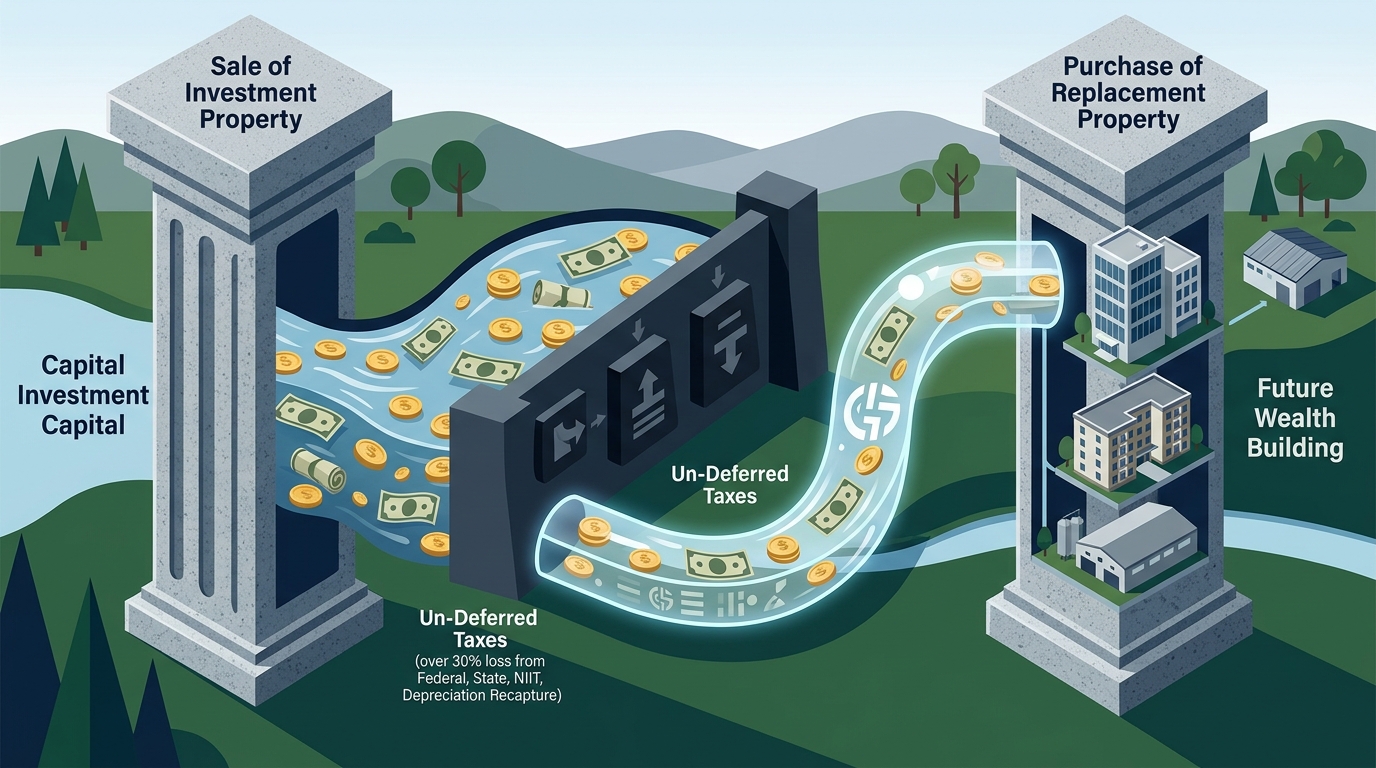
Investors selling investment property face a significant financial hurdle if they do not utilize a 1031 exchange. According to recent tax data, the combined federal and state tax burden on a typical investment property sale can exceed 30% of the realized gain. This includes long-term capital gains rates, the net investment income tax, and depreciation recapture. By using a qualified intermediary, investors can defer these taxes entirely, preserving more capital for future wealth building. Granite Exchange Services has guided over 20,000 investors through this process since 2000, ensuring compliance with strict IRS deadlines. (1031 Exchange Alaska Granite)
What is a 1031 Exchange?
A 1031 exchange, named after Section 1031 of the Internal Revenue Code, allows investors to defer paying capital gains taxes on the sale of investment property. The core requirement is that the proceeds must be reinvested in a "like-kind" property of equal or greater value. This mechanism is not a tax exemption but a deferral tool. You do not pay taxes until you eventually sell the replacement property without exchanging again. (1031 Exchange Alabama Granite)
The term "like-kind" refers to the nature of the asset, not its grade or quality. For real estate, this means any investment property in the United States can be exchanged for any other investment property in the United States. This flexibility allows investors to swap a single-family rental for a multifamily building, or commercial office space for raw land. The discipline of a private bank ensures that every transaction is handled with precision and security. (1031 Exchange Arkansas Granite)
To qualify, the property must be held for productive use in a trade or business or for investment. Personal residences, such as your primary home, do not qualify. However, vacation homes that are rented out for a significant portion of the year may qualify if they meet specific IRS usage tests. Understanding these nuances is critical to avoiding unexpected tax liabilities. (1031 Exchange Colorado Flat)
Exchange Structures Explained
Not all exchanges are created equal. The structure you choose depends on your timeline, financial goals, and the nature of the properties involved. Granite Exchange Services offers specialized guidance for each type to ensure seamless execution.
Delayed (Forward) Exchange
This is the most common structure. You sell your relinquished property first and then identify and acquire a replacement property within strict timeframes. The process begins with the sale of your current asset. You must identify potential replacement properties within 45 days. You then have 180 days to close on the replacement property. This structure is ideal for investors who want to sell first and find a new property later.
Reverse Exchange
A reverse exchange allows you to acquire the replacement property before selling your relinquished property. This is useful in competitive markets where finding the right property first is challenging. The IRS provides a safe harbor under Rev. Proc. 2000-37 for these transactions. An Exchange Accommodation Titleholder (EAT) holds the title to the property during the exchange period. This structure requires careful planning and coordination to meet all IRS requirements.
Construction or Improvement Exchange
Also known as a build-to-suit exchange, this structure allows you to use exchange funds to make improvements on the replacement property. The improvements must be completed within the 180-day exchange period. This is particularly useful for investors looking to add value to a property immediately after acquisition. The funds are held by the qualified intermediary until the improvements are verified.
Delaware Statutory Trust (DST)
A DST allows investors to participate in fractional ownership of institutional-grade real estate. This is a passive investment option for those who do not want to manage physical properties. DSTs are often used in complex multi-asset exchanges. The trust is managed by a sponsor, and investors receive distributions from the property's income.
Critical Deadlines and Rules
Timing is the most critical factor in a successful 1031 exchange. Missing a deadline can result in the disqualification of the entire exchange, leading to immediate tax liability. The IRS enforces these deadlines strictly, with no extensions granted for weekends or holidays.
The 45-Day Identification Rule requires you to identify potential replacement properties in writing within 45 days of closing on the relinquished property. You can identify up to three properties regardless of their value. Alternatively, you can identify more than three properties as long as their total fair market value does not exceed 200% of the value of the relinquished property. This is known as the 200% rule.
The 180-Day Completion Rule requires you to close on the replacement property within 180 days of closing on the relinquished property. These two periods run concurrently. If the 45th day falls on a weekend or holiday, the deadline is extended to the next business day. However, the 180-day deadline is absolute. If the 180th day falls on a weekend or holiday, the deadline is also extended to the next business day.
Understanding boot is essential for minimizing taxes. Boot refers to any non-like-kind property received in the exchange, such as cash or debt relief. Receiving boot triggers immediate taxation on the amount of the boot. To defer all taxes, you must reinvest all proceeds and acquire property of equal or greater value and equity.
Fund Security and Compliance
The safety of your funds is paramount in a 1031 exchange. A qualified intermediary holds your proceeds during the exchange period. This custody arrangement is the real product of the intermediary service. Granite Exchange Services uses segregated, FDIC-insured accounts for every exchange. Your funds are never commingled with other clients' funds.
One account is created per exchange, in your exchange's name. This ensures complete transparency and security. The intermediary acts solely as a facilitator and does not provide legal, tax, or investment advice. It is crucial to work with a certified professional to navigate the complexities of fund handling. The discipline of a private bank ensures that every transaction is handled with precision and security.
Compliance with IRS regulations is non-negotiable. The intermediary must ensure that you do not have actual or constructive receipt of the funds. If you touch the money, the exchange fails. The intermediary handles all communication with the parties involved in the transaction. This includes the buyer of your relinquished property and the seller of your replacement property.
State-Specific Tax Considerations
While Section 1031 is a federal tax provision, state tax laws vary significantly. Some states conform to federal rules, while others have their own requirements or exemptions. Understanding your state's specific rules is crucial for accurate tax planning.
For example, California tracks deferred gains with an annual FTB filing. Investors selling California property must file Form 3840 annually until the gain is recognized. This adds an administrative burden that must be accounted for in your long-term tax strategy. Texas, on the other hand, has no state income tax, making it a favorable destination for investors looking to minimize their overall tax burden.
Alabama taxes capital gains as ordinary income at rates up to 5%. Combined with federal taxes, the total burden can be significant. However, a 1031 exchange defers all of it. Alaska has no state income tax, making it one of the most tax-favorable home states for 1031 investors. Investors in these states can leverage the exchange to maximize their after-tax returns.
Other states may have specific withholding requirements for non-resident sellers. For instance, some states require buyers to withhold a percentage of the purchase price from non-resident sellers. A fully deferred 1031 exchange can exempt the seller from this withholding if proper documentation is provided. Always consult with a tax advisor to understand your state's specific rules.
Key Takeaways
- Deferral Power: A 1031 exchange defers all federal and state capital gains taxes, allowing you to reinvest 100% of your proceeds.
- Strict Deadlines: You have 45 days to identify replacement property and 180 days to close. These deadlines are absolute.
- Fund Security: Funds are held in segregated, FDIC-insured accounts with no commingling, ensuring your capital is safe.
- Exchange Types: Delayed, reverse, construction, and DST exchanges offer flexibility for different investment strategies.
- State Variations: State tax laws differ significantly. California tracks deferred gains, while Texas and Alaska offer tax advantages.
- Expert Guidance: Working with a CES®-certified specialist ensures compliance and reduces the risk of exchange failure.
- Long-Term Wealth: Over 25 years, Granite Exchange Services has safeguarded over $1 billion in client funds.
Frequently Asked Questions
What is the difference between a delayed and reverse exchange?
A delayed exchange requires you to sell the relinquished property first, then identify and acquire the replacement property. A reverse exchange allows you to acquire the replacement property before selling the relinquished property, using an Exchange Accommodation Titleholder to hold title temporarily.
Can I exchange a personal residence for an investment property?
No. The property being sold must be held for investment or productive use in a trade or business. Personal residences do not qualify for a 1031 exchange. However, vacation homes that are rented out may qualify if they meet specific IRS usage tests.
What happens if I miss the 45-day identification deadline?
If you miss the 45-day deadline, the exchange is disqualified. You will be liable for all capital gains taxes on the sale of the relinquished property. There are no extensions for this deadline, even if the 45th day falls on a weekend or holiday.
How are my funds secured during the exchange?
Your funds are held in segregated, FDIC-insured accounts in your exchange's name. They are never commingled with other clients' funds. This ensures that your capital is protected and available for the acquisition of your replacement property.
Does a 1031 exchange eliminate taxes forever?
No. A 1031 exchange defers taxes. You will eventually pay capital gains taxes when you sell the replacement property without exchanging again. However, you can continue to exchange indefinitely, deferring taxes for as long as you hold the property.
What is boot in a 1031 exchange?
Boot is any non-like-kind property received in the exchange, such as cash or debt relief. Receiving boot triggers immediate taxation on the amount of the boot. To defer all taxes, you must reinvest all proceeds and acquire property of equal or greater value and equity.
Can I exchange property in one state for property in another?
Yes. You can exchange investment property in any state for investment property in any other state. This is a common strategy for investors looking to move to a more tax-friendly state or diversify their portfolio geographically.
Start Your Exchange
Do not let taxes erode your investment returns. Granite Exchange Services provides expert guidance to ensure your 1031 exchange is seamless and compliant. With over 25 years of experience and 20,000+ exchanges completed, we are your trusted partner in wealth preservation. Start your exchange today and secure your financial future.